India is moving toward cleaner and more sustainable fuel options, and ethanol blended fuels are
becoming a major part of this transformation. Rising petrol prices, increasing pollution, and
dependence on imported crude oil have pushed the government to promote alternatives like E20 and
E85 fuel. These fuels are designed to reduce emissions, support farmers, and decrease fuel imports.
Many people hear terms like E20 and E85 but do not fully understand what they mean. The concept
is actually simple. The "E" stands for ethanol, while the number represents the percentage of
ethanol mixed with petrol.
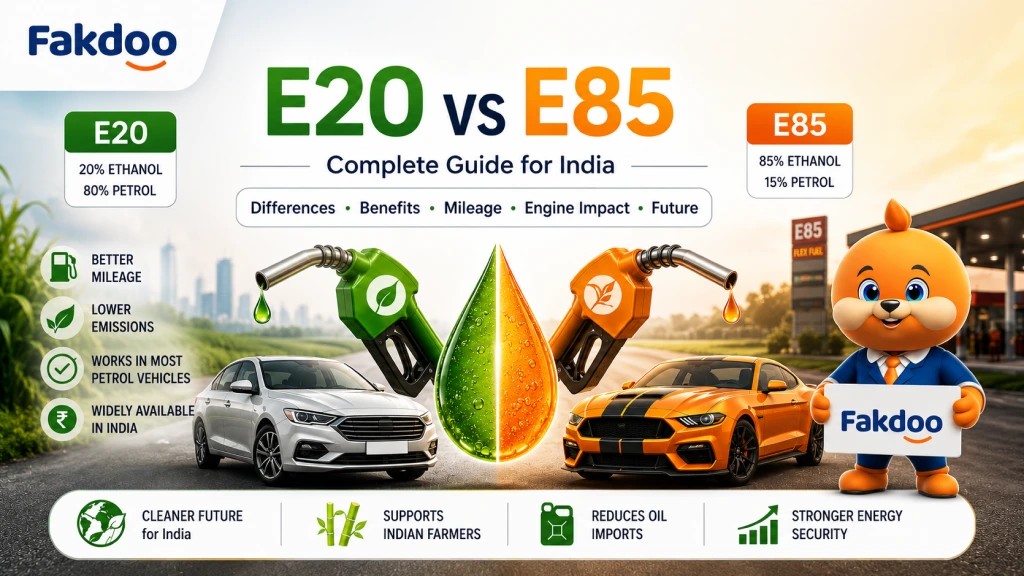
- E20 fuel contains: 20% ethanol + 80% petrol
- E85 fuel contains: 85% ethanol + 15% petrol
Even though both are ethanol blended fuels, they are very different in terms of compatibility,
mileage, engine requirements, and future use in India.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
UNDERSTANDING ETHANOL BLENDED FUELS
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
Ethanol blended fuel is a mixture of petrol and ethanol used in vehicles with internal combustion
engines. Ethanol is a biofuel made mainly from sugarcane, maize, and other agricultural products.
Since ethanol comes from plant-based sources, it is considered renewable and cleaner than
traditional fossil fuels.
India is one of the world's largest sugarcane producers, making ethanol production more practical
for the country. By blending ethanol with petrol, India can reduce crude oil imports while
supporting farmers and rural industries.
Some key benefits of ethanol blended fuels include:
• Reduced dependence on imported oil
• Lower vehicle emissions
• Better energy security
• Support for Indian agriculture
• Cleaner combustion compared to pure petrol
Countries like Brazil and the United States have already adopted ethanol fuels on a large scale.
India is now following a similar path through aggressive ethanol blending programs.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
WHAT IS ETHANOL FUEL?
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
Ethanol fuel is alcohol-based fuel used either independently or mixed with petrol. It is produced
through the fermentation of crops rich in sugar and starch.
The production process includes:
1. Collecting sugarcane or grain-based raw materials
2. Fermentation process to create alcohol
3. Distillation and purification
4. Blending with petrol
Ethanol contains oxygen, which helps fuel burn more efficiently inside the engine. This cleaner
combustion reduces certain harmful emissions released from vehicles.
However, ethanol also has lower energy density compared to petrol. This means vehicles may
consume slightly more fuel when using higher ethanol blends.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
WHY INDIA IS PROMOTING ETHANOL BLENDING
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
India imports a massive amount of crude oil every year. Global fuel price fluctuations directly
affect petrol and diesel prices in the country. Ethanol blending helps reduce this dependence.
The Indian government is promoting ethanol because it offers multiple advantages:
• Reduces oil import expenses
• Improves energy independence
• Supports farmers through ethanol production
• Lowers harmful vehicle emissions
• Strengthens rural economies
The government's Ethanol Blended Petrol Programme (EBP) has already achieved major progress.
India is rapidly moving toward higher ethanol blending targets to improve fuel sustainability.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
WHAT IS E20 FUEL?
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
E20 is a fuel blend containing 20% ethanol and 80% petrol. It is currently the main ethanol blend
being promoted for regular passenger vehicles in India.
The biggest advantage of E20 is that many modern petrol vehicles can use it with minimal
modifications. This makes it easier for India to adopt E20 nationwide without massive
infrastructure changes.
Key Features of E20 Fuel:
• Contains 20% ethanol
• Compatible with many new petrol vehicles
• Lower emissions compared to normal petrol
• Helps reduce fuel imports
• Easier transition for consumers
E20 is considered a practical middle-ground solution because it balances sustainability and
vehicle compatibility.
VEHICLES COMPATIBLE WITH E20
─────────────────────────────
Most newly manufactured petrol cars and bikes in India are now designed for E20 compatibility.
Major automobile companies are already updating engines and fuel systems accordingly.
Brands supporting E20-ready vehicles include:
Maruti Suzuki | Honda | Tata Motors | ToyotaHyundai | Bajaj | TVS
Older vehicles may still run on E20, but long-term usage depends on engine design and fuel
system materials.
Possible issues in incompatible vehicles include:
• Reduced mileage
• Fuel line corrosion
• Engine knocking
• Increased maintenance
Vehicle owners should always check the manufacturer's recommendation before using higher
ethanol blends.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
WHAT IS E85 FUEL?
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
E85 is a high-ethanol fuel blend containing 85% ethanol and 15% petrol. Unlike E20, E85 requires
specially designed engines known as Flex-Fuel Vehicles (FFVs).
E85 is much cleaner than regular petrol and significantly reduces fossil fuel usage. However, it
is not suitable for standard petrol engines.
Key Features of E85 Fuel:
- Contains 85% ethanol
- Requires flex-fuel technology
- Produces lower emissions
- Higher octane rating
- Reduces petroleum dependency
Countries like Brazil widely use E85 and similar ethanol-rich fuels, but India is still in the
early stages of adoption.
──────────────────────────────────────────
FLEX-FUEL VEHICLES AND E85 COMPATIBILITY
──────────────────────────────────────────
Flex-fuel vehicles are specially engineered to run on multiple ethanol-petrol blends, including
E20 and E85.
These vehicles use:
- Ethanol-resistant fuel systems
- Advanced sensors
- Modified engine calibration
- Specialized fuel injection systems
The biggest advantage of flex-fuel vehicles is flexibility. Drivers can use petrol, ethanol
blends, or a combination depending on availability and pricing.
However, E85 adoption in India still faces challenges such as:
- Limited fuel station availability
- Lack of flex-fuel infrastructure
- Higher fuel consumption
- Low consumer awareness
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
E20 VS E85: MAJOR DIFFERENCES
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
Although both fuels contain ethanol, E20 and E85 differ significantly.
FUEL COMPOSITION :
E20 → 20% ethanol + 80% petrol
E85 → 85% ethanol + 15% petrol
VEHICLE COMPATIBILITY:
E20 → Works with many modern petrol vehicles
E85 → Requires flex-fuel vehicles
MILEAGE DIFFERENCE:
E20 → Causes only slight mileage reduction
E85 → Reduces mileage more because ethanol has lower energy density
ENVIRONMENTAL IMPACT:
E20 → Reduces emissions moderately
E85 → Provides much greater emission reduction
INFRASTRUCTURE REQUIREMENT:
E20 → Needs minimal infrastructure changes
E85 → Requires major fuel distribution upgrades
For India's current conditions, E20 is more practical for mass adoption, while E85 represents
a future-focused fuel solution.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
ADVANTAGES OF E20 FUEL
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
E20 offers several benefits for Indian consumers and the economy.
Benefits of E20:
- Lower pollution compared to petrol
- Reduced crude oil imports
- Better energy security
- Supports farmers and ethanol industries
- Compatible with newer vehicles
- Easier nationwide implementation
For most consumers, E20 provides a cleaner fuel option without requiring major changes in
vehicle ownership or driving habits.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
ADVANTAGES OF E85 FUEL
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
E85 offers even greater environmental advantages because of its high ethanol content.
Benefits of E85:
- Significantly lower emissions
- Cleaner combustion
- Reduced fossil fuel dependence
- Higher octane rating
- Supports renewable energy goals
E85 can also improve performance in certain high-compression engines due to ethanol's naturally
high octane properties.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
CHALLENGES OF ETHANOL BLENDED FUELS IN INDIA
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
Despite the advantages, ethanol blending also comes with challenges.
Major Challenges:
• Limited awareness among consumers
• Compatibility concerns in older vehicles
• Lower mileage in high ethanol blends
• Infrastructure limitations
• Water-intensive crop dependency
• Need for flex-fuel vehicle expansion
Balancing food production and ethanol manufacturing is another long-term concern because
ethanol relies heavily on agricultural resources.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
GOVERNMENT POLICIES AND ETHANOL MISSION
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
India's ethanol roadmap is driven by strong government initiatives focused on cleaner mobility
and reduced oil imports.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
INDIA'S ETHANOL BLENDING PROGRAM
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
The Ethanol Blended Petrol Programme aims to increase ethanol usage across India.
Key objectives include:
- Reducing fuel imports
- Lowering emissions
- Supporting sugarcane farmers
- Promoting domestic fuel production
India has already achieved significant progress toward higher ethanol blending targets.
───────────────────────────
FUTURE GOALS FOR BIOFUELS
───────────────────────────
India plans to expand biofuel adoption in the coming years through:
• Flex-fuel vehicle promotion
• Increased ethanol production
• Stronger fuel infrastructure
• Cleaner transportation systems
• Investment in renewable energy technologies.
The long-term goal is to make India less dependent on imported fossil fuels.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
IS E20 OR E85 BETTER FOR INDIAN CONSUMERS?
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
For most Indian consumers today, E20 is the more practical choice.
Why E20 Is Better Currently:
- Widely compatible with modern vehicles
- Easier fuel availability
- Lower transition costs
- Minimal infrastructure changes
E85 is more suitable for future adoption when flex-fuel vehicles become more common in India.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
FUTURE OF ETHANOL FUELS IN INDIA
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
India's future fuel strategy will likely include:
- Ethanol blending
- Electric vehicles
- Hydrogen fuel technologies
- Renewable energy integration
Ethanol fuels will play a major role during the transition toward cleaner transportation. As
infrastructure improves and flex-fuel vehicles increase, higher ethanol blends may become
more common.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
CONCLUSION
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
E20 and E85 fuels represent important steps toward cleaner and more sustainable transportation
in India. While E20 is designed for immediate large-scale adoption, E85 showcases the long-term
future of renewable fuel technology.
India's ethanol mission is not just about fuel — it is about reducing imports, supporting
farmers, improving air quality, and building energy security. Although challenges remain,
ethanol blended fuels are expected to become a major part of India's automotive future.
For everyday consumers, understanding the differences between E20 and E85 is important before
choosing fuel options or buying future vehicles.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
FAQs
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
1. Can regular petrol cars use E20 fuel?
Most modern petrol vehicles can use E20 fuel, but older vehicles should follow
manufacturer recommendations.
2. Is E85 available in India?
E85 availability is currently limited because India's flex-fuel infrastructure is
still developing.
3. Does ethanol reduce mileage?
Yes, higher ethanol blends may slightly reduce mileage because ethanol contains lower
energy density than petrol.
4. What is a flex-fuel vehicle?
A flex-fuel vehicle can run on multiple ethanol-petrol blends, including E85.
5. Is ethanol fuel environmentally friendly?
Yes, ethanol burns cleaner than petrol and helps reduce harmful vehicle emissions.
 Discounts on Package Ads